For more stories like this, sign up for the PLANSPONSOR NEWSDash daily newsletter.
Thought Leadership September 30, 2026
Beyond Pensions: Managing Post Retirement Benefit Risk
Charles DeClara of MetLife explains how retiree medical and retiree life benefit buyouts can reduce volatility, simplify administration and provide greater financial certainty.
Sponsored by
MetLife
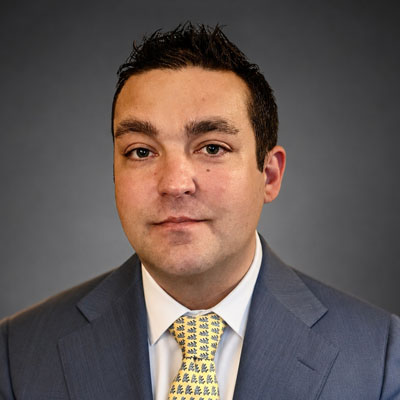
Charles DeClara
Pension risk transfers (PRTs) have been a significant trend in the retirement plan industry since 2012, when several large corporate defined benefit plan sponsors completed landmark transactions that transferred billions of dollars of pension liabilities to insurance companies.
While pension annuity buyout purchases had existed for decades, annual transaction volumes were typically about $1 billion before the market expanded dramatically following the large deals of 2012. Today, PRTs are a widely used de-risking strategy for plan sponsors.
However, pensions are not the only long-term obligations affecting employers’ financials. According to Charles DeClara, vice president and head of post-retirement benefits at MetLife, retiree medical and other post-retirement benefits can create substantial financial uncertainty for organizations.
“Healthcare cost trends, interest rates and longevity assumptions can affect both the balance sheet and income statement, creating financial uncertainty that can persist for decades,” DeClara says. “According to MetLife’s Post Retirement Benefits Poll, 85% of plan sponsors say post-retirement benefits receive significant attention from corporate management because of their financial impact.”
According to MetLife’s Post Retirement Benefits Poll, 85% of plan sponsors say post-retirement benefits receive significant attention from corporate management because of their financial impact.
Since the COVID-19 pandemic, many employers have experienced increased healthcare, retiree medical and end-of-life-related benefit costs, prompting renewed scrutiny of these long-term liabilities. As a result, according to DeClara, corporate management is increasingly assessing whether retaining these obligations remains the most efficient use of capital and resources.
“As organizations face a combination of rising benefit costs, longevity-related risks and market uncertainty, they are looking for strategies that provide greater predictability and control,” he says. “Retiree medical buyouts, for example, can transfer future obligations and associated risks to an insurer, helping reduce volatility, simplify administration and create a more predictable financial outcome.”
Benefits of Retiree Medical and Retiree Life Buyouts
Organizations typically pursue retiree medical and retiree life buyouts to gain financial certainty, reduce administrative complexity and improve strategic flexibility. Like pension risk transfer transactions, retiree medical and retiree life buyouts shift long-term obligations to an insurer and can reduce balance sheet volatility. “Sponsors that are familiar with pension risk transfer strategies may find the evaluation and implementation of retiree benefit buyouts to be a natural extension of their broader de-risking efforts,” DeClara says.
According to DeClara, the “pros” of retiree benefit buyouts include:
- Removing liabilities from the balance sheet and transferring interest rate, investment and longevity risks to an insurer;
- Reducing administrative responsibilities, including recordkeeping, claims support and participant communications;
- Generating positive financial results, as transaction costs may be lower than the company’s existing balance sheet obligation and may allow recognition of some or all associated accumulated other comprehensive income or AOCI; and,
- Replacing an open-ended liability with a more predictable obligation that supports broader business and capital management goals.
DeClara notes that retiree medical buyouts can benefit both employers and retirees. MetLife’s research found that lifetime security of retiree healthcare benefits is the most important benefit plan sponsors associate with a retiree medical buyout.
“When obligations are transferred to an insurer with expertise in managing long-duration liabilities, retirees gain the backing of an organization whose core business is managing and delivering those commitments over time,” DeClara says. “Because retiree medical and retiree life buyouts are irrevocable transactions, they can strengthen retiree confidence in the long-term security of their benefits.”
He adds that these transactions are often structured to minimize disruption. The experience is typically designed to provide continuity for retirees throughout the transition.
Addressing Common Misconceptions
One of the most common misconceptions about retiree medical and retiree life buyouts, DeClara says, is that they require benefit reductions.
“These transactions are designed to preserve the benefits that have already been promised to retirees,” he explains. Once the obligation is transferred, the insurer assumes responsibility for delivering benefits according to the terms established before the transaction.
Another misconception is that these transactions are overly complex or appropriate only for the largest organizations. DeClara says the market has matured significantly over the past decade, making risk transfers relevant for a broader range of sponsors.
He also cautions against viewing buyouts solely as cost-cutting exercises.
“While financial considerations are certainly important, many plan sponsors are equally focused on reducing volatility, simplifying administration, strengthening benefit security and creating greater certainty around long-term obligations,” he says. “As a result, the decision is often part of a broader risk management and capital allocation strategy rather than a purely financial one.”
Evaluating a Risk Transfer Strategy
According to DeClara, successful outcomes begin with a clear understanding of organizational objectives. Some plan sponsors are motivated by reducing financial volatility, while others prioritize administrative simplification, balance sheet management or long-term strategic planning.
“With the right preparation and experienced partners, sponsors can develop solutions that align financial goals with their commitment to retirees,” DeClara says.
He recommends that organizations evaluate the characteristics of their obligations, including liability size, funding considerations and available financing or pension-surplus strategies that could support a broader de-risking approach.
“Sponsors with well-funded pension plans, for example, may have additional flexibility when evaluating retiree medical or life obligations,” DeClara says.
Just as important is understanding the retiree population and the desired long-term outcome for participants.
“The most effective decisions balance financial stewardship with benefit security and are grounded in a clear understanding of both organizational objectives and retiree needs,” he says.
The timeline of a post-retirement benefit risk transfer can vary depending on the size and complexity of the liability, the quality of the underlying data, and the organization’s objectives. Following an initial evaluation of the retiree population and benefits involved, sponsors typically move through data preparation, pricing analysis, transaction structuring and implementation planning.
According to DeClara, one of the most important factors influencing timing is preparation.
“Sponsors that have clear objectives, strong governance and accurate participant data are typically better positioned to evaluate opportunities and move efficiently through the process,” he says. “In our experience, the groundwork completed before a transaction is often the most important determinant of a successful outcome.”
DeClara notes, however, that the most successful transactions are not necessarily the fastest; they are the ones that are thoughtfully planned, aligned with organizational objectives and designed to create long-term certainty for both the sponsor and retirees.
Post-retirement benefit liabilities may be legacy obligations, but their financial impact is very current. Retiree medical and retiree life buyouts can help organizations convert uncertain long-term obligations into more predictable and manageable commitments.
“Ultimately, the question is not simply whether to transfer risk, but whether doing so helps create greater certainty for the organization while supporting the commitments made to retirees,” he says. —Rebecca Moore
©2026 MetLife Services and Solutions, LLC
Metropolitan Life Insurance Company | New York, NY 10166
Metropolitan Tower Life Insurance Company | Lincoln, NE, 68516
L5816559[exp0827][All States/Territories Except][]
Sponsored by
« The DC Imperative: Advance Investment Solutions to Strengthen the Retirement Lifeline